
Self - Credit Builder & Cards
- Rating
- 4.7
- 38K Reviews
- Downloads
- 1M+
- Age Rating
- Everyone
App Specs
- Version
- 10.0.0
- Updated
- Requires
- 7.0
- Price
- Free
Screenshots
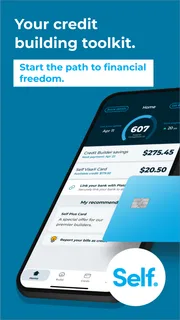
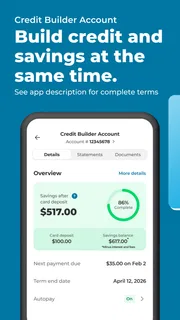
Our Review
 Analysis byMileapps
For someone trying to establish credit, the hard part is often finding a first step that feels manageable rather than confusing. Self – Credit Builder & Cash is a finance app from Self Financial, Inc. that centers on a credit-building account and a savings outcome. I see its appeal in that combination: it gives a credit newcomer a defined routine to consider instead of asking them to begin with a conventional credit card. It still calls for careful budgeting, though; a product intended to build credit is only useful if its payments fit your real life.
What “free” means when the app involves a financial product
The app is free to download, and its age rating is Everyone. That answers the basic app-store cost question, but it should not be confused with a promise that every financial product or activity inside the app is free. Before enrolling, I would read the current plan terms closely and check the total payment commitment, any applicable fees, and the conditions for receiving funds. Those are the details that matter when deciding whether the service is affordable, not the download price alone.
That distinction is especially important for anyone comparing Self with free credit-score tools. A score-monitoring app may let you check information without taking on a payment schedule; Self’s central proposition is different because its credit-building approach involves payments and money set aside. I would treat the app as a gateway to a financial product, not as a no-cost shortcut to a better score. The free access makes it easy to explore, while the decision to participate deserves the same scrutiny as any other financial commitment.
Why the routine may be more useful than the score screen
The practical value here is not simply seeing a number change. For a person with little or limited credit history, a predictable payment routine can create a reason to practice the habits lenders look for: choosing an amount that fits the budget, keeping track of due dates, and following through month after month. The savings element can make that routine feel tangible. Instead of paying toward an ordinary bill that disappears once settled, the account is designed to leave the user with money at the end of the process, subject to its terms.
I would still keep expectations measured. Credit reporting does not make a score rise on command, and the result depends on a person’s broader credit file and behavior. Self is better approached as one structured part of a longer plan than as a quick repair button. If someone already has a steady history of on-time payments and several active accounts, adding another commitment may bring less practical value than keeping existing accounts in good standing and managing balances carefully.
Where it fits among common alternatives
Compared with a conventional secured credit card, a credit-builder account can be easier to understand for someone who is uncomfortable borrowing on a card or worried about overspending. A card can offer day-to-day purchasing flexibility, but it also requires careful balance management; a payment-based builder account focuses more directly on sticking to a scheduled contribution. Neither route is automatically better. The right choice depends on whether the user needs practice managing revolving credit or prefers a more fixed routine that also builds savings.
Compared with a free score tracker, Self asks for more involvement and a financial commitment, while a tracker is usually more useful for observation than for creating payment history. I would use a tracker if my only goal were to keep an eye on credit information. I would consider Self if I wanted a defined credit-building process and could comfortably make the required payments. Someone who needs cash immediately should also compare other options: a credit-building plan is not the same thing as readily available spending money, and the account’s structure and terms should guide that decision.
The app has a substantial audience, with an average rating of 4.4 from around 91,000 ratings and more than a million installs. Those figures suggest that many people have tried it, but they cannot tell you whether a particular plan suits your budget or circumstances. I would use the app’s own terms and my monthly cash flow as the deciding factors rather than treating popularity as proof that it is the right financial move for everyone.
Using Self with a plan, not just a download
Jumping into the world of credit scores can be overwhelming, especially if you're just starting out on your financial journey or aiming to rebuild your credit. That's where Self – Credit Builder & Cash comes in. This app offers a straightforward approach to improving your credit score while providing a savings boost. Let's dive into the ins and outs of this app, and I'll share my personal experience with you.
Getting Started with Self
First things first, downloading and setting up Self – Credit Builder & Cash is a breeze. Available on both Android and iOS, the app’s interface is clean and intuitive, making navigation smooth even for first-time users. Once you’re in, you’re greeted with a simple sign-up process that guides you through creating an account and setting your financial goals.
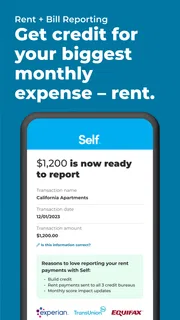
What I really appreciate about Self is its transparency. Right from the start, the app lays out how its credit builder loan works. Essentially, you’re taking out a small loan that’s held in a certificate of deposit (CD) account. You make monthly payments which are reported to the major credit bureaus, and upon completion, you receive the money back. It's a win-win for building your credit and saving simultaneously.
The Nitty-Gritty of Credit Building
Now, let's talk about the core functionality of Self. The app's primary feature is its credit builder account. This is where you choose a plan that fits your budget, with monthly payments ranging from $25 to $150. The flexibility here is fantastic, allowing you to select a payment plan that aligns with your financial situation.
Throughout my usage, I've noticed how Self diligently sends reminders to ensure that I don’t miss any payments. This feature is crucial because timely payments are key to improving credit scores. Over time, as your payments are reported to credit bureaus, you’ll likely see a positive impact on your credit score.
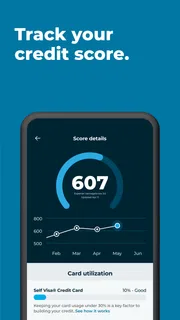
It's also worth mentioning that Self provides detailed insights into your credit history and score, which is a great tool for tracking your progress. The app breaks down complex credit information into easy-to-understand chunks, making it accessible for everyone.
The Nitty-Gritty: Fitting payments into real life
The plan choice deserves more attention than a quick tap during setup. I’d first look at my ordinary monthly bills, then choose only an amount I could keep paying in a tight month as well as a comfortable one. A payment that looks small beside rent or groceries can still become a problem if income varies or an unexpected expense arrives. The useful test is not “Can I afford this today?” but “Can I maintain this schedule without relying on a credit card or dipping into emergency money?”
For example, imagine someone paid every two weeks who is rebuilding after a period of missed bills. They could review their pay dates, set aside the monthly amount as soon as income arrives, and use reminders as a prompt to verify that the money is available. That makes the app’s routine a budgeting exercise as well as a credit-related one. If the plan competes with essentials, I would pause rather than risk missing a payment in pursuit of a score goal.
A less obvious trade-off is that a reminder helps with memory, not affordability. Notifications can reduce the chance of overlooking a due date, but they cannot make an overcommitted budget workable. I’d treat them as a final checkpoint and keep a separate calendar or budget note if I already manage several bills across different dates. That small bit of preparation can make a fixed payment easier to handle without assuming the app will solve cash-flow problems on its own.
Additional Features: More Than Just Credit Building
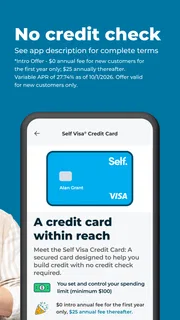
Apart from its core service, Self offers a unique feature called the Self Visa Credit Card. Available after making at least three successful monthly payments, this secured credit card provides an additional avenue for building credit. It’s a handy tool for those looking to further enhance their credit portfolio.
What’s more, the app includes a referral program where you can invite friends and earn rewards when they sign up and make payments. It's a nice little perk that adds more value to the app.
Deciding whether to add the card or use referrals
I would treat the secured card as a separate decision rather than assuming it is a necessary next step. A card can be useful if the person wants to learn to manage purchases and pay a balance responsibly, but it also adds another account to monitor. Before applying, I’d consider whether I already have a card I can use carefully and whether a new account fits my priorities. The key is not to collect credit products for their own sake; it is to choose a manageable mix and keep every obligation organized.
The referral feature is even less central to the financial decision. It may be a pleasant extra for someone who already uses the service and knows a friend who genuinely wants it, but I wouldn’t count possible rewards as part of the plan’s value or budget. A referral should not be the reason to enroll, and friends should be encouraged to review the terms for themselves rather than taking a recommendation as a guarantee of results.
Personal Experience and Verdict
So, what’s it like using Self on a day-to-day basis? In my experience, it's been surprisingly seamless. The app sends notifications to keep you on track, and the customer support is responsive, which is a huge plus. I also find the educational content within the app quite beneficial, offering tips and tricks on maintaining and improving credit scores.
One aspect I truly appreciate is the sense of empowerment and control I’ve gained over my financial future. Being able to watch my credit score improve and knowing that I’m building a financial safety net is incredibly rewarding.
Who is likely to get the most from it?
I’d put Self on the shortlist for someone starting with a thin credit file who wants a guided routine, has enough room in the budget for regular payments, and values the savings component. It may also suit a person who has missed payments in the past and wants a more deliberate system for keeping future obligations visible. The app’s current version is 7.3.0, and it has been available since March 30, 2018; those details place it as an established service, but they don’t replace a personal check of the current account terms.
I’d be more cautious if income is unpredictable, essential bills are already difficult to cover, or the main need is immediate access to cash. In those situations, a new payment obligation may add pressure instead of helping. Someone who already has a credit card and reliably pays it in full may get more mileage from maintaining that habit than adding another product. And if all that’s needed is visibility into a score, a tracking tool without a payment commitment may be a better fit.
Before signing up, I’d answer three practical questions for myself: What will the total commitment be under the plan I choose? What happens if I need to stop or change course? And how does the account report activity, including the timing of any updates? Reading the terms and checking the in-app explanations before committing can prevent assumptions about fees, access to funds, or score timing. No app can promise a particular credit outcome, so I’d judge progress by consistent habits and the full credit picture rather than a single number.
In conclusion, if you’re looking for an app that combines credit building with savings, Self is definitely worth checking out. It’s ideal for those new to credit or looking to repair their credit history, all while setting aside a little nest egg. The app’s user-friendly interface, comprehensive features, and educational resources make it a standout choice in the financial app landscape.
Pros and Cons
Pros
- Helps improve credit score effectively.
- Easy-to-navigate user interface.
- Offers educational financial tips.
- Automated savings for convenience.
- Secure and private data management.
Cons
- Monthly fee might be high for some.
- Limited customer support options.
- Not available in all regions.
- Requires bank account for setup.
- No option for joint accounts.
Frequently Asked Questions
What is Self – Credit Builder & Cash, and how does it work?
Self – Credit Builder & Cash is a financial app designed to help users build their credit scores while saving money. It works by allowing you to take out a small loan, which is held in a certificate of deposit (CD) account. You make monthly payments towards this loan, and once it’s paid off, the funds are released to you. This process helps to establish a positive credit history.
How does using Self impact my credit score?
Using Self can positively impact your credit score as long as you make timely payments. The app reports your payment history to the major credit bureaus, which helps build your credit profile over time. However, missing payments can negatively affect your score, so commitment to the payment schedule is crucial.
What fees are associated with using Self?
Self charges a one-time, non-refundable administrative fee when you open an account. Additionally, there may be interest fees associated with the loan. It's important to review all fee details before committing to ensure you understand the total cost of using the service and how it fits into your financial plan.
Is my money safe with Self?
Yes, your money is held in a secure, FDIC-insured account through Self’s banking partners. This means your funds are protected up to the legal limit. Self also employs standard security measures to protect your personal and financial information throughout your use of the app.
What happens if I miss a payment on my Self account?
If you miss a payment on your Self account, it can negatively affect your credit score, as missed payments are reported to the credit bureaus. Additionally, late fees may apply. It’s important to reach out to Self’s customer support if you encounter financial difficulties, as they may offer assistance or solutions to help you manage your account.

Download Self - Credit Builder & Cards
Close Matches in This Category
 Google WalletFinance4.4
 Airtel: Recharge, Bank & LoansFinance4.0
 DANA Indonesia Digital WalletFinance4.5
 Binance: Buy Bitcoin & CryptoFinance4.8
 Inter Banking & Money TransferFinance4.4
 Cash AppFinance4.7
 PayPal - Pay, Send, SaveFinance4.2
 MetaTrader 5 — Forex, StocksFinance4.7